Your claim was accepted, the adjuster came out, and the estimate arrived. Then your roofer priced the same job and the numbers do not line up. That gap is common after a storm in the Midlands, and it does not automatically mean anyone acted in bad faith. A first estimate is usually written quickly, from what an adjuster can see in one visit, using a pricing database and a standard list of line items. Roofs are not standard, and some of what they need only shows up once the old shingles come off.
This article picks up where the step-by-step roof insurance claim process leaves off: the claim exists, an estimate is on the table, and you think it is short. It covers why that happens, how a missing item gets documented, and the formal options your policy may give you if the two sides still disagree. None of these steps is guaranteed to change the number. They are ways to put better evidence in front of the insurer and to use the dispute tools your policy already contains.
Why first estimates often come in low
Adjusters work through a lot of roofs after a large hail or wind event, and the estimate they write reflects what they could verify on the day. A few patterns explain most of the gaps homeowners run into.
- Hidden conditions. Decking under the shingles cannot be seen from the surface. If sheathing turns out to be soft, delaminated or rotted when the roof is torn off, it was not on the original estimate because nobody could see it.
- Components left off the scope. Estimates sometimes list shingles and underlayment but leave out the parts that finish the roof: drip edge, starter strip, ridge cap, hip and ridge shingles, flashing, pipe boots and vents.
- Code-required items. When a roof is replaced, current building code can require work the old roof never had, such as drip edge or underlayment details. Whether your policy pays for code items depends on its ordinance or law coverage, so check that wording.
- Steep and high charges. Steep pitches and tall roofs need extra safety equipment and slow the crew down. Estimating software usually has separate line items for this, and they are easy to miss.
- Overhead and profit. When a job needs several trades, such as a roofer plus a gutter installer or a carpenter, a general contractor coordinates the work. Some estimates leave out the overhead and profit that coordination carries.
- Measurement differences. A roof measured from satellite imagery and a roof measured by hand can differ, and waste for hips, valleys and cut-up roof lines varies by shape.
None of these is exotic. They are the ordinary differences between a quick estimate and the scope a roofer has to build to, and they are the items supplements are usually about.
What a supplement is
A supplement is a request to add to or correct an existing claim estimate. It is not a new claim and it is not an appeal. It says, in effect: here is an item your estimate does not include, here is why the job needs it, and here is the proof. Some supplements are filed before work starts, when the gap is visible on paper. Others come mid-job, when tear-off exposes damaged decking or a hidden problem that nobody could have priced earlier.
South Carolina does not let a residential roofer negotiate an insurance claim on your behalf. What your roofer can do is inspect, photograph, measure and write an estimate, and you can use that evidence in your own dealings with the insurer. Our guide to hiring a roofing contractor in South Carolina explains the rule and what it means in practice.
How a supplement gets documented
A supplement stands or falls on its evidence. A vague note that the estimate "seems low" gives an adjuster nothing to approve. A clear package ties each missing item to a reason and a photo.
Photos that show the item, and where it is
Each photo should make it obvious what it shows and where on the roof it is. Wide shots establish the slope; close-ups show the condition. For decking found during tear-off, photograph the damaged sheets in place before they are replaced, with something in the frame for scale.
Measurements
Roof area, pitch on each slope, linear feet of eaves, rakes, ridges, hips and valleys. If the insurer measured from imagery and your roofer measured by hand, say so and show the difference slope by slope.
A line-item comparison
The most useful document is a side-by-side: the insurer estimate in one column, the roofer scope in the other, with each difference called out. For every added or changed line, give a one-sentence reason, such as "required by code at replacement," "not visible until tear-off," or "steep pitch on rear slopes." Where a manufacturer installation instruction or the local code calls for a component, cite it.
- Keep a copy of every estimate version and every letter.
- Write down the date, the person you spoke with and what was said on each call.
- Send requests in writing, even if you discussed them by phone first.
- Ask for a written answer on each line item, not just a revised total.
Asking for a reinspection
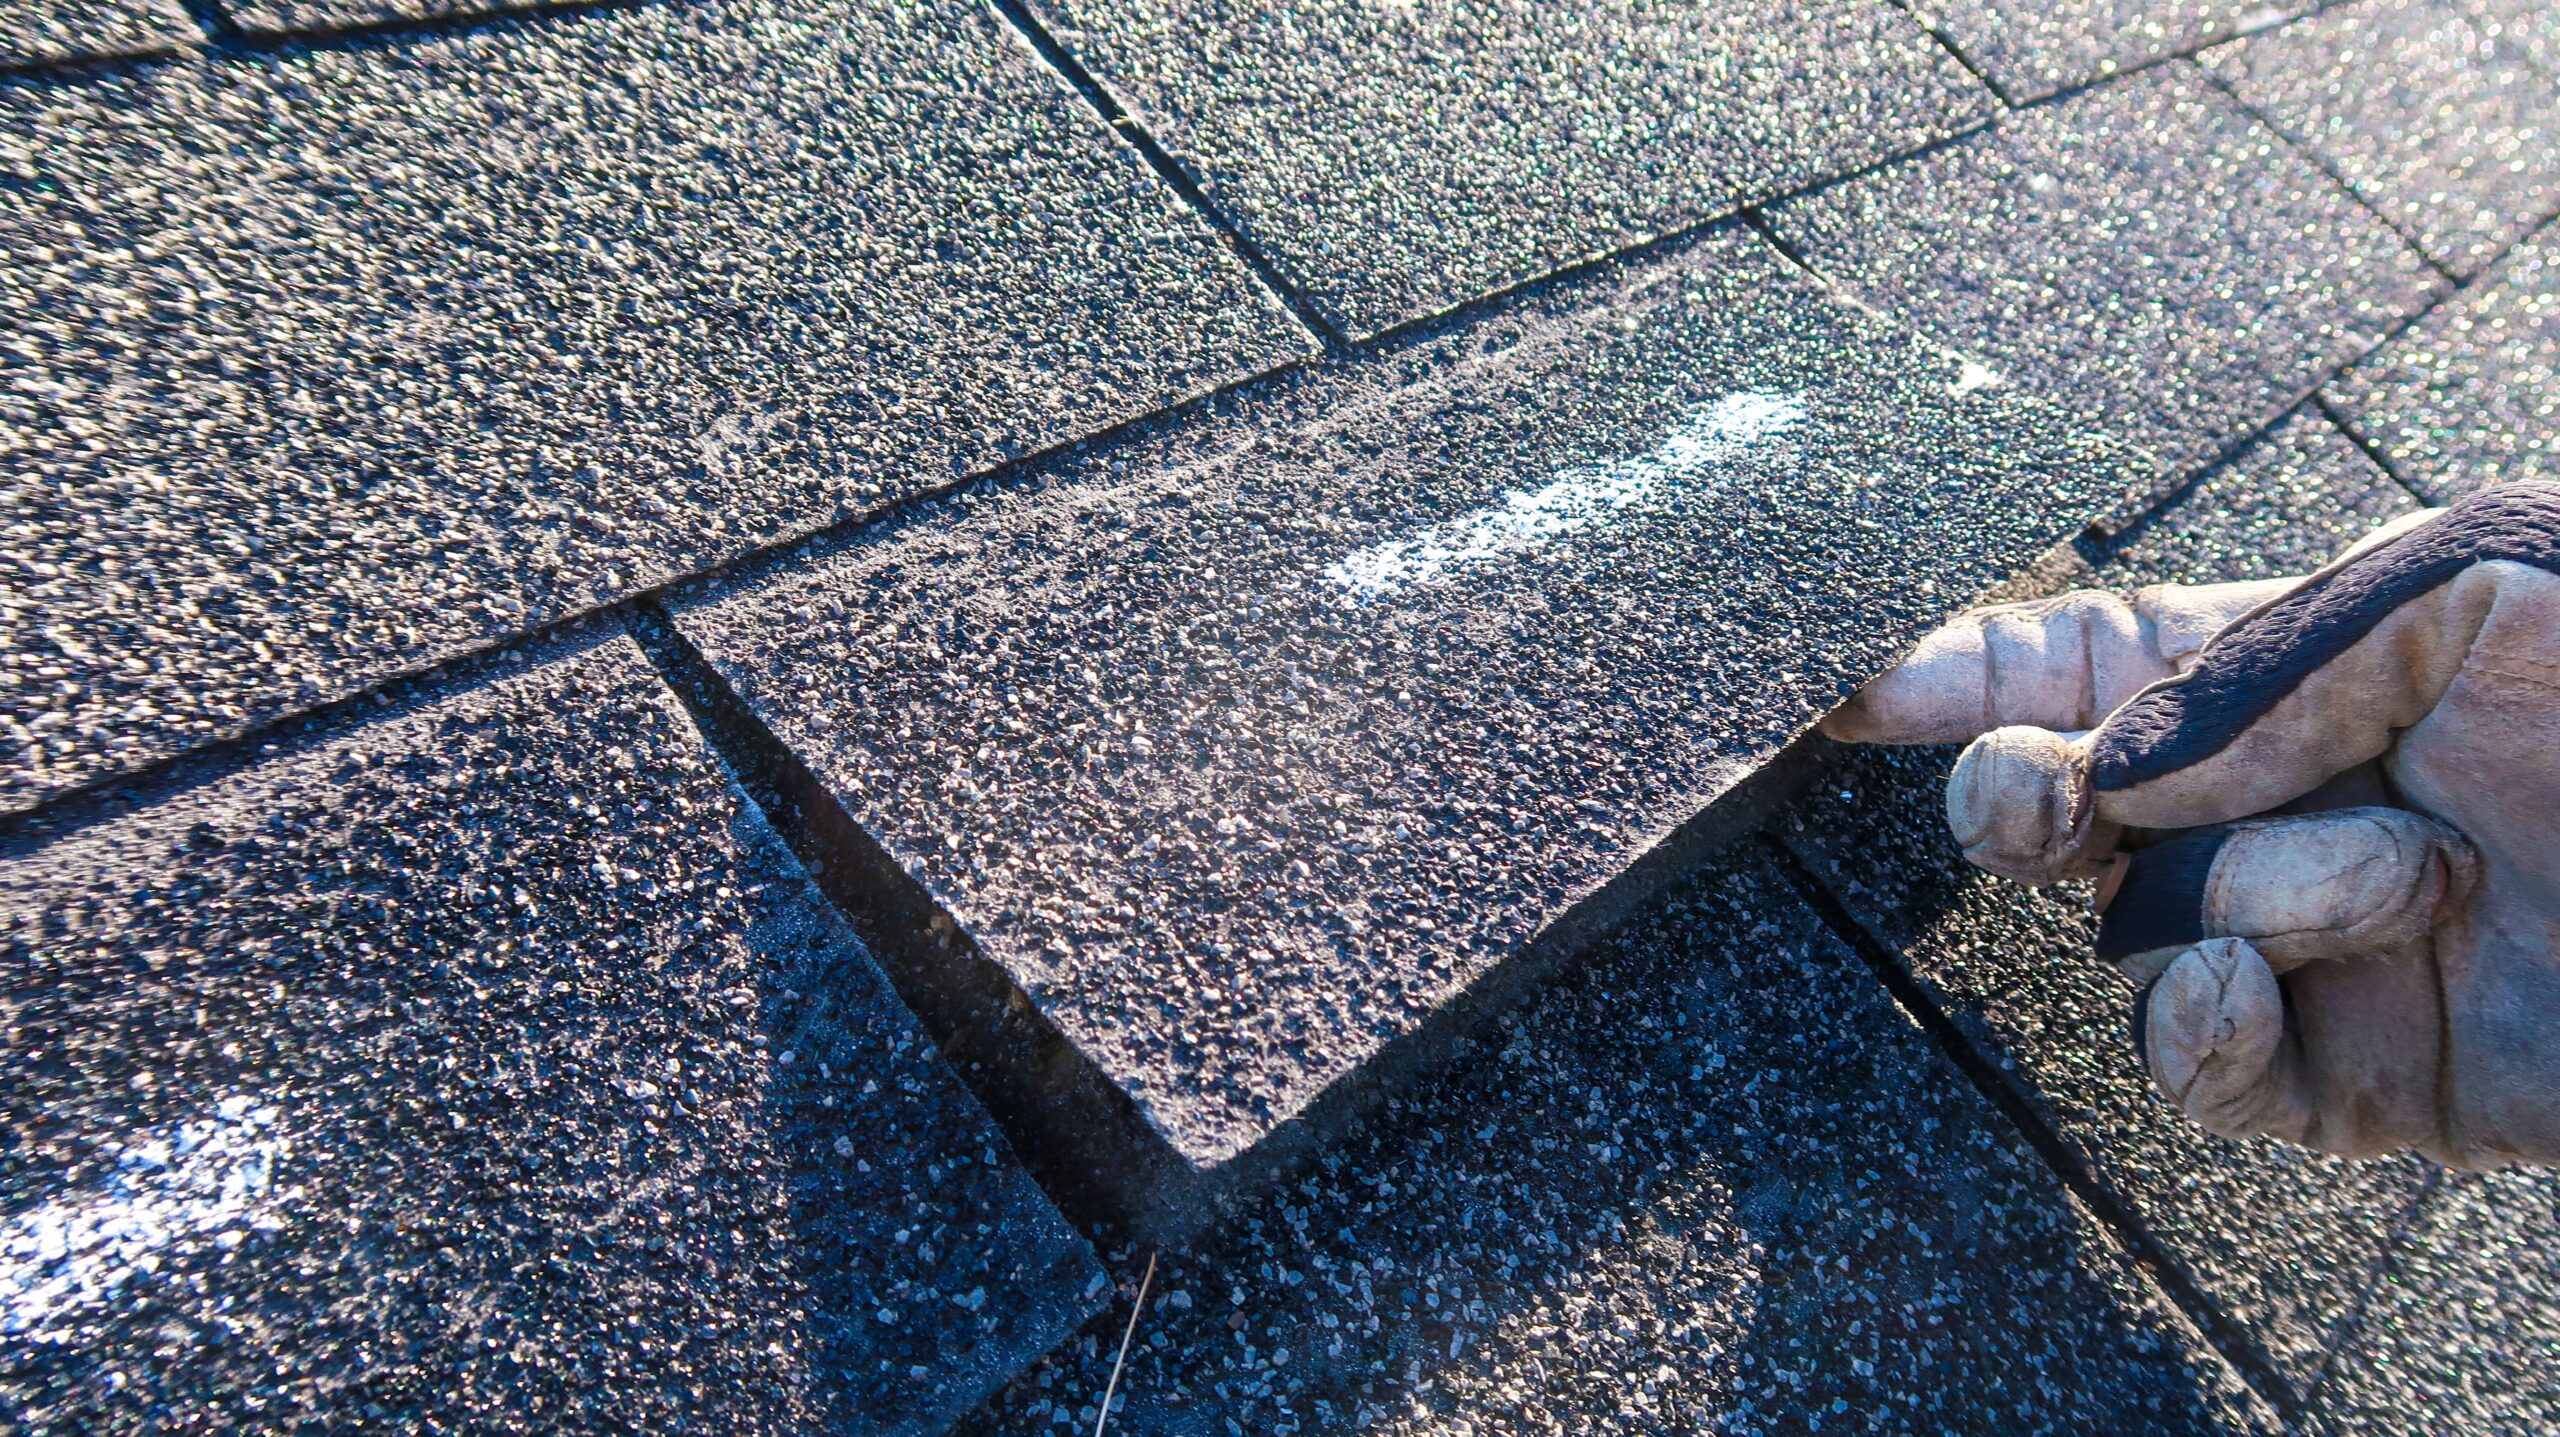
Sometimes the disagreement is not about a missing line but about the damage itself: the adjuster counted fewer hits, called creased shingles old wear, or did not get on a steep slope. In that case you can ask the insurer to send someone back out. Put the request in writing, explain specifically what you believe was missed, and attach the photos. It helps to ask that your roofer be present so the same areas get looked at together.
A reinspection may confirm the original estimate, change part of it, or change all of it. If the storm also left hail marks or lifted shingles you want to understand better before that visit, our articles on hail damage to roofs in Columbia and spotting wind damage on a roof show what adjusters look for.
The appraisal clause, in general terms
Most homeowners policies contain an appraisal provision for disagreements about the amount of a loss. The wording varies by insurer and by policy form, so read yours before relying on any summary, including this one. In general terms, it tends to work like this:
- Either you or the insurer makes a written demand for appraisal.
- Each side picks its own appraiser.
- The two appraisers try to agree on the amount of the loss.
- If they cannot agree, an umpire resolves the disagreement; the appraisers usually choose the umpire, and many policies let a court appoint one if they cannot.
- An agreement signed by two of the three typically sets the amount.
- Each side usually pays its own appraiser, and the umpire and other appraisal costs are typically shared.
Appraisal is generally limited to how much the loss is worth. It usually does not decide whether something is covered at all, and some policies set conditions or deadlines for demanding it. Because you pay your own appraiser and part of the umpire, it costs money, and the result can come in higher, lower or close to what the insurer already offered. If you are considering it, read the exact appraisal wording in your policy and ask your agent or an attorney how it applies to your claim.
A complaint or a public adjuster
If you believe your insurer is not responding, is not explaining its decisions, or is handling the claim unfairly, the South Carolina Department of Insurance accepts consumer complaints about insurers. Treat this as a last resort after you have put your requests in writing and given the insurer time to answer. Include the claim number, a short timeline and copies of your correspondence. The Department can look into how a claim was handled; it is not a way to have someone else rewrite the estimate.
Another option is to hire a public adjuster, a licensed professional who works for you, not the insurer, and can negotiate the claim on your behalf. South Carolina rewrote its public adjuster law in 2026, covering licensing, fees and your right to cancel the contract. The contractor guide linked above summarizes the new rules; read that and check any adjuster’s license before you sign.
Keeping the roof protected while you sort it out
A disagreement over the number does not stop rain. Tarp or temporarily repair active leaks so the damage does not grow, keep receipts, and photograph the temporary work. Most policies expect you to take reasonable steps to prevent further damage. For storm repair, tarping and the rest of our storm resources in one place, see our page on storm damage roof repair in Columbia, SC.
If you have an insurance estimate and want a roofer to measure, photograph and price the job line by line so you can compare, ask us for a free inspection.